Docs
 Support


Timing Matters as Much as Cost
Interest rates have risen. Debt costs more, and equity investors are more selective than they were two years ago. A mine plan that looked acceptable back then may no longer work today. A life-of-mine (LOM) plan built when capital was cheap may now have problems that do not show yet. Decide where to cut, where to keep spending, and how to keep the Ore Reserve (Mineral Reserve under NI 43-101 and S-K 1300) statement accurate while you do it.
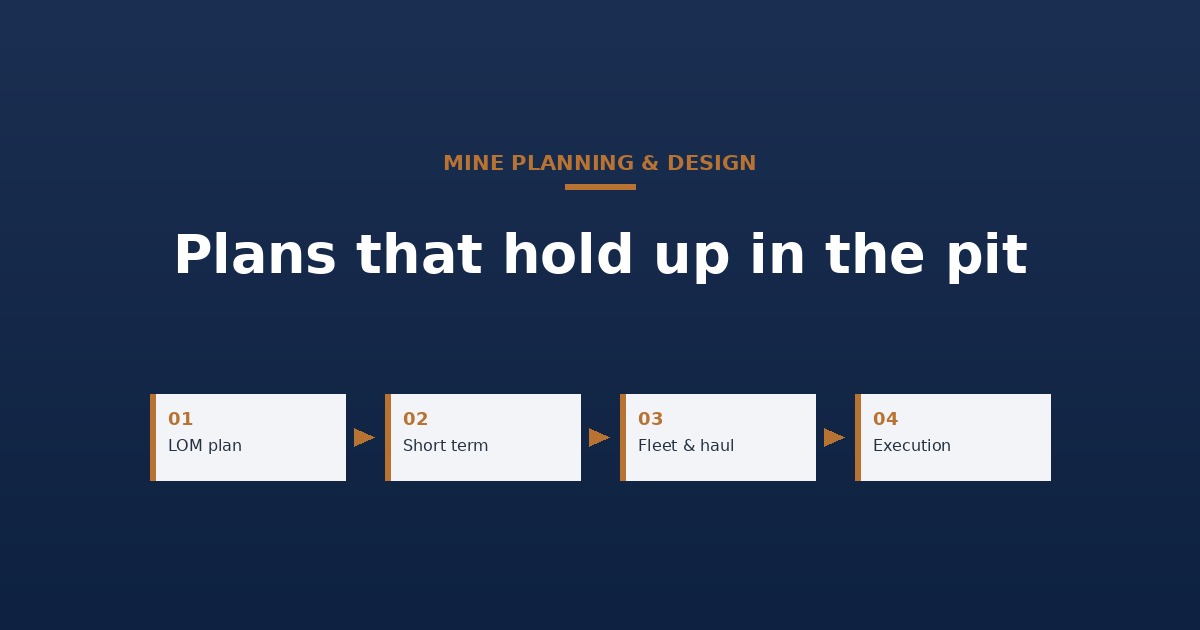
| Planning Steps When Capital Costs More | |
| Step 1: Reset the cut-off grade Recalculate cut-off grade using current discount rate, mining cost, and metal price assumptions |
Which blocks are economic today? Does the Ore Reserve boundary move? |
| ▼ | |
| Step 2: Resequence the LOM schedule Schedule high-grade, low-strip-ratio material earlier in the mining sequence. Defer capital-intensive pushbacks |
When is capital spending at its peak? Can it be reduced or delayed? |
| ▼ | |
| Step 3: Validate short-term plans against the block model Confirm that the next 3 to 6 months of mining match the revised LOM plan |
Are we mining the right material now? Does grade control follow the plan? |
| ▼ | |
| Step 4: Update the Ore Reserve statement Under NI 43-101, S-K 1300, or JORC Code, revised assumptions require a documented reserve update |
Can the Qualified Person (NI 43-101, S-K 1300) or Competent Person (JORC) defend the sign-off? Does the reserve still match current economics? |
Review the Cut-off Grade Before the Budget
When capital gets harder to raise, the first reaction is to cut the budget. That is understandable. But if you cut spending before you recheck the cut-off grade, you may be protecting the wrong blocks. A cut-off grade changes with metal price, processing cost, mining cost, and the cost of capital. When the discount rate increases from 5% to 8%, the net present value of material mined late in the LOM drops. In the pushback example below, it falls from $200 million to $160 million or less. Blocks that were economic at a lower discount rate may no longer be economic.
Start the recalculation with the block model. Take the mining cost per tonne, the processing cost per tonne, the payable metal price, and the recovery factor, then compute the break-even grade. Add a capital charge for the equipment, infrastructure or sustaining capital tied to that block. If the cut-off grade rises, material near the pit limits becomes uneconomic and the Ore Reserve becomes smaller. That is the correct result.
The Qualified Person (NI 43-101, S-K 1300) or Competent Person (JORC) must disclose the assumptions behind the cut-off grade (NI 43-101, section 3.4; S-K 1300, §229.1302; JORC Code 2012, Table 1, Section 4). If those assumptions have changed and the reserve statement has not been updated, the disclosure is out of date. Regulators and investors will both see it. Do the cut-off grade analysis before the budget discussion.
Here is an example. Take a copper open pit with a mining cost of $2.10/t, processing cost of $8.50/t of ore, a copper price of $3.80/lb and recovery of 88%. Under those assumptions the break-even grade is close to 0.14% Cu. Raising the discount rate increases the capital charge assigned to a major pushback, which lifts the break-even grade by roughly 15%, to about 0.17% Cu. Material with grades between about 0.14% and 0.17% Cu is removed from the Ore Reserve. It stays in the Mineral Resource if it still has reasonable prospects for eventual economic extraction (JORC Code 2012, Clause 20).
Resequence Capital, Then Validate the Short-Term Plan
Once the cut-off grade is set, rework the LOM schedule. When capital is expensive, plan for early cash flow. Schedule high-grade, low-strip-ratio ore in the first years of the LOM plan and defer major capital expenditures, mainly large pushbacks and new fleet purchases, until the project has generated enough cash to fund them internally or until financing conditions improve.
This is planned sequencing, which is different from high-grading. High-grading mines the highest-grade blocks first. It often leaves lower-grade ore behind under a steep wall or a ramp, where it can only be recovered later with a new pushback, and it compromises pit slope angles. Planned sequencing follows the block model, changes the mining direction on purpose, and records the reasons in the LOM plan. Write these rules into the mine planning and design process so another planner can repeat the plan and an auditor can check it.
Consider a major pushback requiring $180 million of pre-stripping capital spread over 18 months. Discounting that spend at 5% brings it to roughly $173 million in present value terms. At 8% it falls to about $169.5 million. The discounted cost of the capital changes little over an 18-month spending period. What changes is the value of the ore the pushback exposes, because that revenue arrives years later and is discounted much more. Take ore worth $200 million NPV at 5%. At 8%, it is worth $159.6 million if it is mined 8 years from now, $173.7 million if it is mined 5 years from now, and $183.8 million if it is mined 3 years from now. The margin is lost in the ore value.
The steps above follow this reasoning from the economic assumptions to the reserve statement. Each step has to use actual data: dispatch records, reconciliation results, and the block model. Do not plan on assumptions that have never been checked in the field.
The short-term plan is where the LOM plan is tested in the pit. A revised LOM plan is of no use until it becomes a workable 90-day or 180-day operating plan. A short-term plan review checks that the blocks scheduled for mining in the near term match the revised cut-off grade, fit within current fleet capacity, and meet the head grade targets the processing plant needs to reach its cost-per-tonne goals. When they do not match, the gap shows up in the reconciliation report before it appears in the reserve statement. Act on that earlier warning.
Fleet performance also affects the mining cost. Higher diesel costs, higher tire costs, and higher financing costs on replacement equipment all add to the effective mining cost per tonne. A truck fleet analysis that compares actual payload, cycle times, and fuel consumption against plan assumptions will show whether the mining cost used in the cut-off grade calculation is still accurate. If that cost is too low, the Ore Reserve is overstated.
Keep the Reserve Statement Accurate
The Ore Reserve is a public statement. Under NI 43-101, S-K 1300, and the JORC Code, it has legal consequences. A Qualified Person (NI 43-101, S-K 1300) or Competent Person (JORC) who signs off on a reserve without updating the underlying economic assumptions to current discount rates, costs, and metal prices is taking a disclosure risk. That risk belongs to the company, and in the end to the individual who signed the reserve statement.
Operational teams sometimes resist reserve updates because a smaller reserve looks like bad news. Investors and lenders can plan around a reserve that is based on current economics. A reserve based on old prices and costs will be corrected later, with more damage: through a resource write-down, a project review, or a failed financing.
The mine planning and reserves team (in many companies, part of technical services) should stay connected to the operating plan all year. When economic assumptions change, the reserve needs to be reviewed. When the block model is updated after a large reconciliation variance, the reserve needs to be reviewed. When a major capital expenditure is deferred, such as a pushback, a new phase or a plant expansion, the Ore Reserve may no longer match the plan. The reserve is based on a pit and a schedule that assume the capital is spent on time. If a pushback is deferred by 3 years, for example, its ore is mined later and is worth less after discounting, and some of it may no longer be economic. The Qualified Person or Competent Person should then confirm that the pit design is still economic at current costs, prices and schedule. If the pit design gets smaller, the ore outside it is removed from the Ore Reserve and is reported again as Mineral Resource, because it is still mineralized material that may be mined in the future. Inside the pit design, a higher cut-off grade can also change marginal ore to waste.
For operations reporting under multiple frameworks, say a Canadian company with a project in a JORC Code jurisdiction, the consistency of assumptions across reporting standards matters. The cut-off grade, the modifying factors, and the SMU assumptions must be consistent whether you are producing a NI 43-101 technical report or a JORC Code compliant resource and reserve statement. It shows whether the planning team and the technical reporting team use the same numbers.
Summary
Review the cut-off grade before the budget. Then rework the LOM sequence and the short-term plan, and finish with a reserve statement that a Competent Person or Qualified Person can defend. When the cost of capital rises, recalculate each of those steps with current numbers. Do that work early, because delay adds risk.
References
NI 43-101. National Instrument 43-101 Standards of Disclosure for Mineral Projects. Canadian Securities Administrators, 2011 (copy hosted by CIM). https://mrmr.cim.org/media/1017/national-instrument-43-101.pdf
S-K 1300. Regulation S-K, Subpart 229.1300, Disclosure by Registrants Engaged in Mining Operations (17 CFR 229.1300 to 229.1305). U.S. Securities and Exchange Commission, 2018, current text in the eCFR. https://www.ecfr.gov/current/title-17/chapter-II/part-229/subpart-229.1300
JORC Code 2012. Australasian Code for Reporting of Exploration Results, Mineral Resources and Ore Reserves (The JORC Code, 2012 Edition). Joint Ore Reserves Committee of the AusIMM, AIG and Minerals Council of Australia, 2012. https://www.jorc.org/docs/JORC_code_2012.pdf
If you need a review of cut-off grade assumptions, a resequenced LOM plan, or a check that the reserve statement matches current economics, contact the Agmines team at agmines.com/contact. We work in English and Spanish across open pit and underground operations throughout the Americas.
By Alejandro Guerra, Agmines Consulting.
Related Posts
August 9, 2026
Mine Planning for Lower Grades: Reviewing Your Key Assumptions
Many mines that were designed for high-grade, simple orebodies are now pushing deeper or expanding…
August 9, 2026
ESG as Modifying Factors in Ore Reserve Declarations
Mineral Resource and Ore Reserve estimates have always required technical justification. Today they also require…